

NextBlock @NextBlockRWA
The protocol for Insurance RWA Vaults. Tokenizing real insurance portfolios on-chain. The last major asset class without infrastructure Built on Base. nextblock.finance Bahamas, Nassau Joined February 2026-
Tweets260
-
Followers21
-
Following83
-
Likes88
12 months. That is how long a reinsurance contract must stay in force to earn full Solvency II capital credit (Art. 209). Six months left on a treaty over a longer book: roughly half the relief. With one annual quota share, capital relief decays all year and resets at renewal.
$210bn annual infrastructure need in Southeast Asia. MAS says ILS can fund it. The structure works at scale. Programs below $50M stay locked out: cat bond minimums start at $100M regardless of regional demand.
ILS complementary for transferring, funding risks of large infrastructure projects: Singapore’s MAS artemis.bm/news/ils-compl…
52% of insurers name capital management as a key reason to buy facultative reinsurance, up from 44% in 2024 (Willis, 380 buyers). Fac is placed risk by risk. The friction is paid per placement, so capital relief bought that way costs the smallest books the most.
[ANALYSIS] 60% of P&C insurers plan to increase facultative reinsurance purchases to support global expansion and deploy surplus capital, according to WTW. Access the full regional rate and capacity breakdown: intelligentinsurer.com/facultative-re…
Capital architecture is where the cost sits. The structuring bill for a segregated cell, a collateral trust and a rating conversation is broadly flat across deal sizes, so the creative work concentrates on books large enough to absorb it. The small end keeps buying plain capacity because that is what it can afford to buy.
@AMBestCo Discipline reads clearly where a cedent can take a programme to several markets and compare terms. Below the size that supports a tender there is usually one incumbent quote, so discipline and a lack of alternatives produce the same renewal slip.
Net underwriting income near three times last year usually means retentions went up alongside rates. That risk has to be held somewhere, and it is held with capital. For a carrier with under $50m of limit to place, the route to relief is still one renewal date and one counterparty willing to quote it.
Diversification is the easy half of the case. The harder half is what an allocator has to accept to get it a manager in between, a valuation that arrives quarterly, and capital committed until somebody reconciles the year. Those are operational terms rather than risk terms, and they are what keeps most mandates smaller than the appetite sitting behind them.
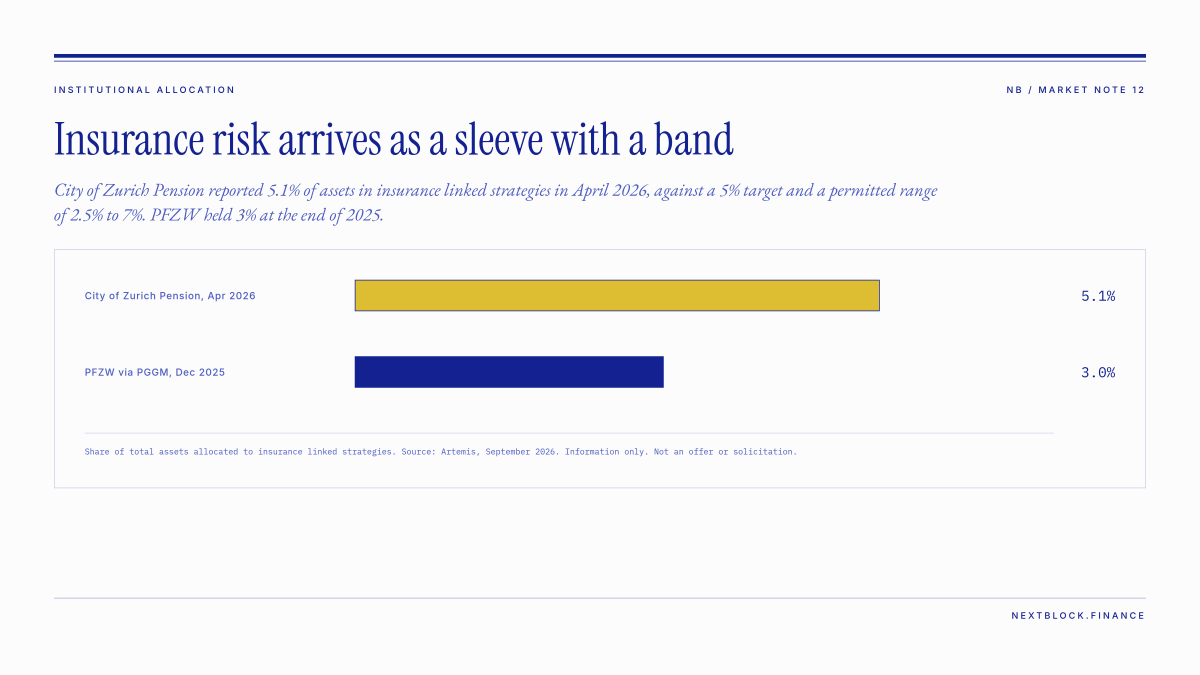
$1.58bn of insurance risk, 5.1% of assets, against a 5% target and a 2.5% to 7% band. That is City of Zurich Pension's ILS allocation, reported in April. An allocator holds it as a sleeve with a band. A treaty has no band: fixed for the term, valued when the cedent reports.
$100bn of health premium ceded to non-affiliated reinsurers in 2025, 47% of everything ceded in the line. Almost all of it placed treaty by treaty. The capital markets side of reinsurance was built around property catastrophe, and a flow this size still sits outside it.
Non-affiliated #health premiums ceded reached nearly $100bn in 2025, accounting for 47% of total health premiums ceded. View: bit.ly/4gWu9Nf #reinsurance #insurance #healthinsurance #healthinsurers #reinsurers #AMBestGlobalReinsurance #AMBestTV #AMBestMarketSegmentReport
Lower three-digit millions, deployed into a single property sidecar at 1/1. That is roughly the size at which third-party capital gets a vehicle of its own. A mid-market carrier's entire ceded programme is often smaller than that one ticket.
[ANALYSIS] Hannover Re deployed its Bermuda property sidecar in the lower three-digit millions at 1/1, board member Silke Sehm confirmed. Read more: ow.ly/G6b450ZOjNs #Reinsurance #ILS
Hong Kong's five-year plan proposes a protected cell regime to cut the cost of issuing insurance-linked securities. The cost of a cession is mostly fixed per deal: legal, actuarial, collateral, admin. The same bill lands on a $200m programme and on a $15m one.
$1.8bn of parametric limit, bought by 39 members who would each be far too small to place it alone. The pool is the access mechanism here, not the cover itself. Most mid-market cedents have no pool to join. They negotiate one programme, once a year, on their own.
CCRIF lifts parametric risk pool coverage another 14.5% to $1.8bn for current policy year artemis.bm/news/ccrif-lif…
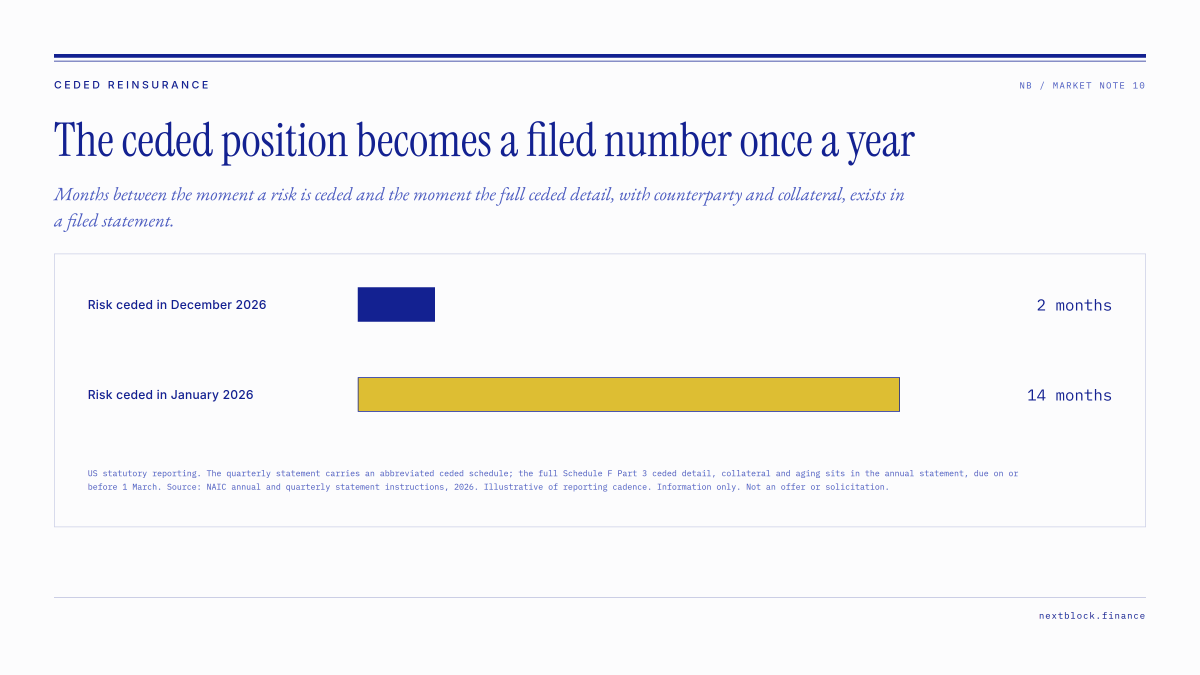
A US insurer files an abbreviated ceded schedule 45 days after each quarter. The full ceded detail, counterparty by counterparty, with collateral and aging, is filed once a year by 1 March. A cession placed in January waits 14 months to become a filed number.
A 2% cut to the risk transfer budget bought $303m more treaty limit. That is what a softening market looks like when the buyer is large enough to redesign the programme. Below about $50m of limit it arrives differently: a slightly better quote from the same reinsurer, on the same structure. The limit does not move, because nobody redesigns a programme that size.
[ANALYSIS] CEA trims 2026 risk transfer budget by 2% to sub-$540M as softening reinsurance rates offset a $303M expansion in treaty limits. The move comes as the authority shifts away from revenue bonds and evaluates long-term capital framework options. Access the complete
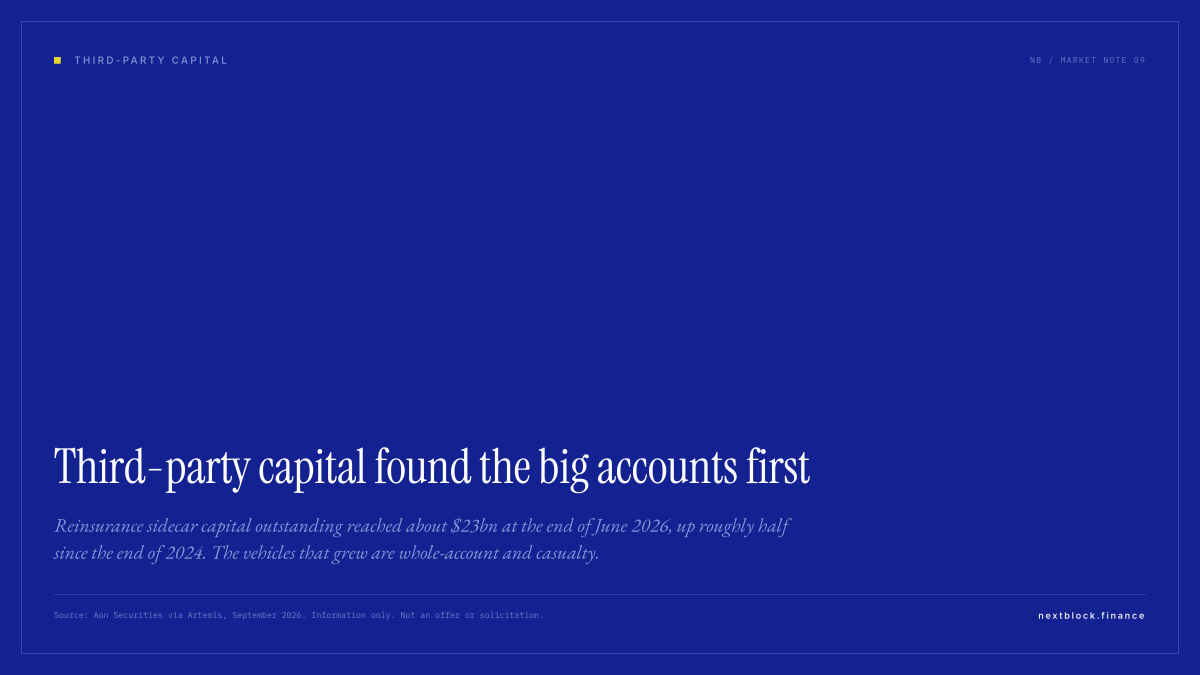
$23bn of reinsurance sidecar capital was outstanding at the end of June, on Aon Securities' count, up roughly half since the end of 2024. A sidecar lets outside investors fund a share of an insurer's own book. S&P said at the Rendez-Vous that the growth now comes from casualty and whole-account vehicles, five to ten year money rather than one to three. Investors will underwrite a sponsor's entire account for a decade. That has not travelled down to the carrier with $30m of limit, which has the same problem and no vehicle that bends to it.
$2.5bn. That is CalPERS' ILS and cat bond valuation at mid-2026, up from $1.9bn six months earlier. Allocators can buy insurance risk when it arrives as a listed instrument. The mid-market quota share does not, and a $15m cedent has no path to that capital.
CalPERS ramps up cat bond and ILS investments to near $2.5bn valuation at mid-year 2026 artemis.bm/news/calpers-r…
KBW now has most executives expecting property cat down 10% or more at 1/1, and warns the actual renewal usually lands softer than the Monte Carlo talk. Softening travels through competition at the renewal table. A cedent who can reach two markets sees the average. A cedent who can reach twelve sees the margin.
Casualty ILS inflows an incremental negative. Cat may soften more than RVS suggests: KBW artemis.bm/news/casualty-…
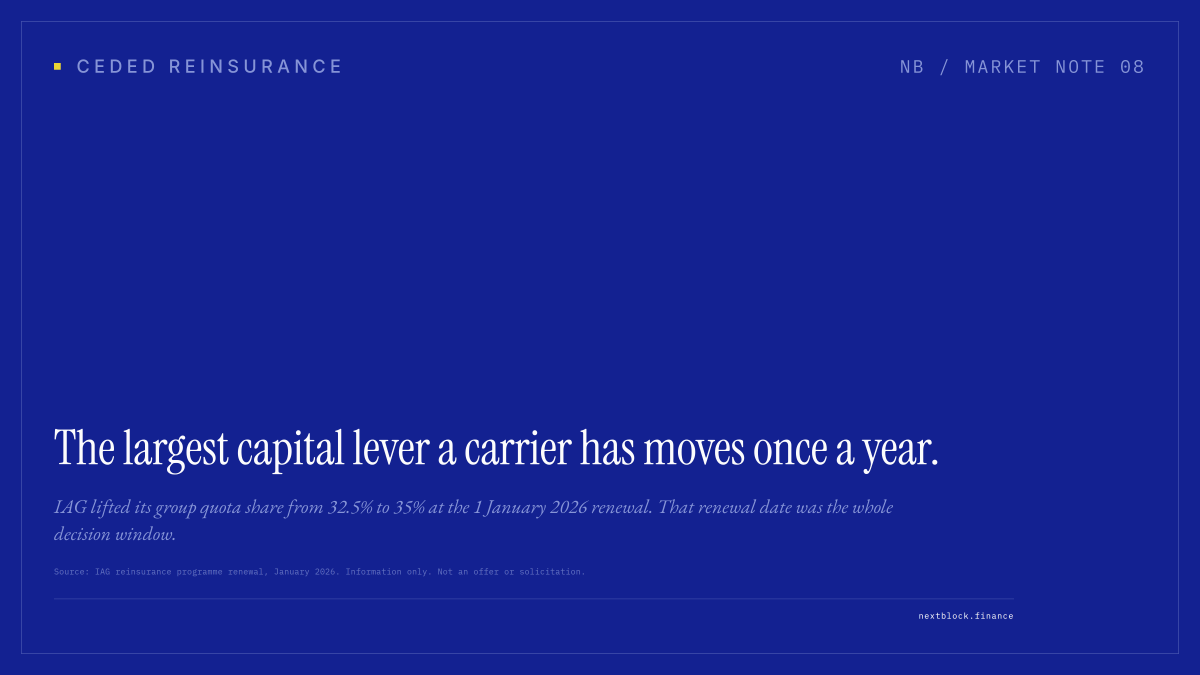
32.5% to 35%. That was IAG's group quota share move at the 1 January 2026 renewal, and the renewal was the only window to make it. A quota share is one of the largest capital levers a carrier has. It reprices once a year, whatever the book does in the other eleven months. A cession that settles continuously moves when the exposure moves. That is what we are building at NextBlock.
The ILS market grew more than 80% in a decade, to about $123bn, with a global workforce still under 2,000. That ratio is standardisation. A cat bond is an instrument, and a small team can run many of them. A mid-market quota share is negotiated one deal at a time.
Over the past decade, the insurance-linked securities (ILS) market has expanded significantly, while keeping its global talent footprint remarkably lean. According to 20Twenty Search Advisor Jason Sykes, this streamlined operational structure shields ILS professionals from the
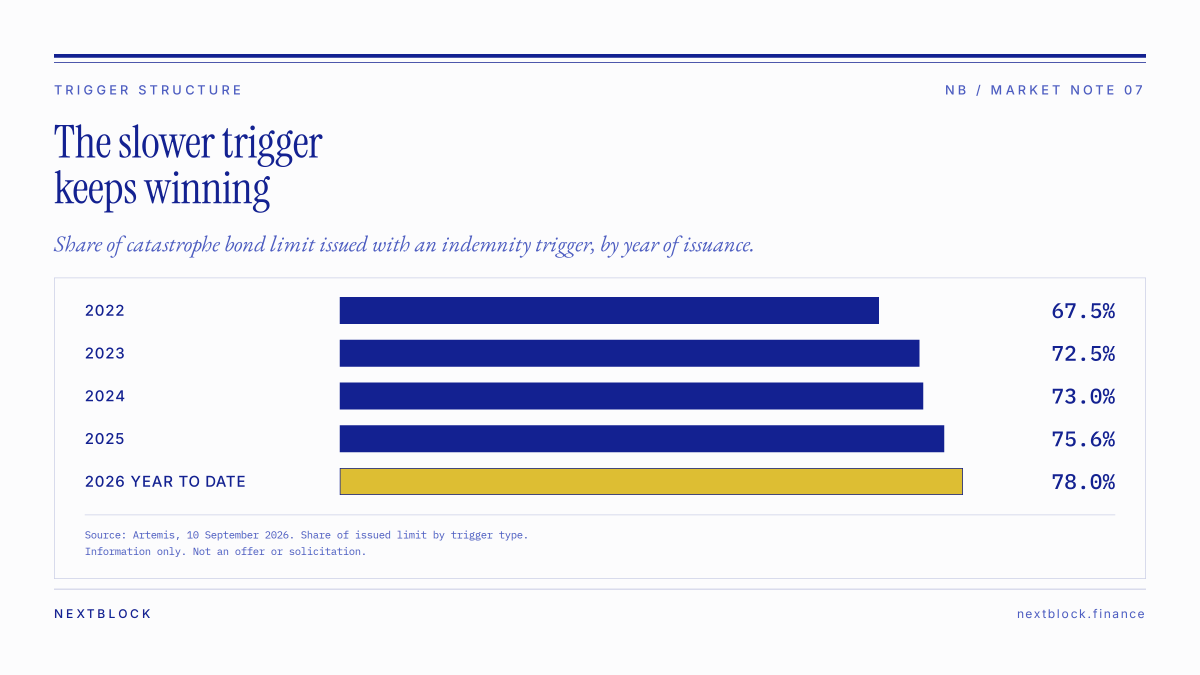
78% of catastrophe bond limit issued in 2026 carries an indemnity trigger, the highest share on record. It was 67.5% in 2022. Indemnity settles slowly: the loss has to be verified first. Sponsors accept it, because a parametric payout can miss the actual claim. @artemisbm

Elgin Haynes @elgindebonair
8 Followers 25 Following
@tonyflosan @tony_flosan
58 Followers 743 Following Chief of Staff @Evertas ($20M raised) | ex- @Cybcubecom ($280M raised) | 👟 Sneaker Hoarder | 🥣 Soggy Cereal Enthusiast

SOUL R @OXSOUL45
821 Followers 1K Following
Centrifuge | Official... @centrifu_ge
113 Followers 3K Following Bringing the full power of onchain finance to asset managers and investors. Built on Ethereum. @rwasummit • @tacoalition

Crypto Whales 🐋 �... @CryptoWhales_X
78K Followers 62K Following Pumpfun/Altcoin Projects Researcher 🔍 | Boost your project with me | 🕰️ 24Hr Active Marketer Admin 👨💼 | DM Me For Promotion Services📩 #BTC #BNB #SOL #ETH
Apespit.eth @Apespit_eth
2K Followers 3K Following TheGrailed fwogs Otherside 10KTF HV-MTL MAYC 2018 & 20144 MAKC Azuki Mutant Hound Mutant Cartel
Alex | Co-Founder Mak... @a_zonneveld
801 Followers 2K Following Connect your strategies to the world | Shopify for Asset Managers | Tokenisation | Digital Assets | Connected Finance | On-chain class of 2017
James InvestAnswers @JamesInvests191
974 Followers 515 Following #Bitcoin #Tesla @Wharton #MathMoneyFreedom Analytics that Defy the Norm: Beyond the Charts
TheStonedMuseum @HiLifeNft
314 Followers 2K Following The first digital drug experience on Solana ⚡️ Enter the museum. Unlock Your NFT. Feel the effect

anton carlo @antoncarlo5
28 Followers 156 Following NextBlock Founder Insurance and Reinsurance Broker Helpet Co-Founder

Happy @HappyGMI
6K Followers 3K Following Ex-Luxury turned Crypto Marketer. Prev. @lvmh @gelatonetwork | Co-Founder @kabbal_io
💵 @qeeHxLHg1GL02yY
22 Followers 760 Following
Alpha.rwa | Adi @alphacyl
10K Followers 4K Following RWA Growth Operator| RWA/Defi research | | @dEURO_com | prev : @shapeShift @AISUEDE | @ADIChain_
Fabio Bautista @bautistafabio
136 Followers 865 Following Abogado Especializado en Derecho del Mercado de Capitales | Tokenización y Blockchain | Real-World Assets | Defi 📈Si lo puedes soñar lo puedes Tokenizar!


ale @0xalerex
1K Followers 271 Following product @lifiprotocol | building the on-chain money stack | founder @ethereumbari
Bermuda:Re+ILS @BermudaRe
2K Followers 492 Following The best source for carefully curated #Bermuda #Insurance & #Reinsurance news and analysis.
Intelligent Insurer @intelligentins
13K Followers 2K Following Intelligent Insurer is a leading publication serving the global #reinsurance #insurance markets. LinkedIn:https://t.co/AbofMdCicy
AM Best @AMBestCo
17K Followers 1K Following AM Best is a global credit rating agency, news publisher and data analytics provider specializing in the insurance industry. Follow @AMBestRatings for ratings.
Dimes @dimesonbase
1K Followers 217 Following We empower creators and builders, meeting them where they are to amplify their impact and add value.
Vault Summit @Vault__Summit
2K Followers 201 Following Vault Summit dives into institutional DeFi strategies beyond stablecoins. Singapore, October 9th, 2026.
Minh Q. Tran @Minh_Q_Tran
31K Followers 16K Following Asset Builder | InvestTech, Insurtech, ImpactTech Investor | Global Venture Studio Leader
Laura Shin @laurashin
297K Followers 6K Following Crypto journalist 🎧 Host @unchained_pod 📚 Author, The Cryptopians 💌 Sign up https://t.co/gf90Q5GrXy Ads [email protected]
Salman Banaei @banamlas
3K Followers 410 Following 🇺🇸 general counsel @PlumeNetwork. posiwid. uber 4.9. ex @secgov @cftc @uniswap @chainalysis @ihsmarkit (nka @spglobal). personal views.
Superstate @SuperstateInc
22K Followers 641 Following Superstate is a financial technology firm reshaping capital markets. Disclosures: https://t.co/hLBnvGJxoc
Superstate @SuperstateFunds
280 Followers 1 Following Our official updates are now at @SuperstateInc. Please follow us there.
Plume @plumenetwork
869K Followers 326 Following Built to Open Institutional Assets. Trusted by Apollo, WisdomTree, DTCC, and more
Centrifuge @centrifuge
94K Followers 368 Following Bringing the full power of onchain finance to asset managers and investors. Built on Ethereum. @rwasummit • @tacoalition
SALVUS Funds @SALVUSFunds
28 Followers 21 Following Licensing | CASP | EMI | Investment Firms | Investment Funds | M&A | MiFID Compliance
RWAStack @RWAStack
84K Followers 4 Following Navigating the frontier of RWA. Research, insights, and the occasional contrarian take. Not financial advice
RWA.xyz @RWA_xyz
46K Followers 11 Following Every tokenized real-world asset, in one place. View the dashboard: 🌐 https://t.co/lkrRJBMVOB 🌐
kobi bendelak- InsurT... @KBendelak
849 Followers 535 Following Kobi is th CEO of InsurTech israel the leader in investments in technology companies to the insurance industry.
James M. Benham | You... @JamesMBenham
4K Followers 3K Following Entrepreneur, Technologist, Bootstrapper. CEO @JBKnowledge & @TerraInsure. Host @InsurTechGeek Podcast. Bestselling Author of “Be Your Own VC.” 📖 YPO.
InsTech @InsTech_London
9K Followers 3K Following InsTech identifies and promotes the use of the best technology, data and analytics within insurance and risk management around the world.
InsurTechTalk @insurtechtalk
8K Followers 770 Following Improving core #insurance activities with #Insurtech. Views expressed are my own.
Sergey Nazarov @SergeyNazarov
185K Followers 48 Following Co-founder of @Chainlink: industry-standard for creating the verifiable web and bringing the whole world onchain. We're Hiring: https://t.co/0xiQfsV9Sz
Chainlink @chainlink
1.4M Followers 25 Following The market-leading oracle platform bringing the global financial system onchain → $34+ trillion enabled
David Tso (dave.base.... @davidtsocy
37K Followers 3K Following Ecosystem & ventures @base. Consumer apps @socialgraphvc @compassdotfun. Alum @Cornell @CUBlockchain @UBC.

Saudi Insurance | ا�... @Saudinsurance
27K Followers 177 Following الحساب الرسمي للجنة الإعلام والتوعية التأمينية، وهي لجنة منبثقة من اللجنة التنفيذية لشركات التأمين السعودية وتحت إشراف هيئة التأمين
Ignas @DefiIgnas
164K Followers 2K Following Subscribe to my DeFi blog to get ahead of the curve 👉 https://t.co/7O0WAdXUnT Co-founder of @PinkBrains_io DeFi Creator Studio
Orient Asset Managers @orientasset
270 Followers 63 Following Orient Asset Managers Ltd is a multi-asset class investment company offering a wide range of investment solutions and services in Sub-Saharan Africa.
Bogdan Burlacu | CRE ... @BogdanBurlacu
2K Followers 82 Following Insights on Data Centers, NNN leases, Construction & Operations, Property Management Retail • Office • Industrial • Data Centers + AI projects
ted @tednotlasso
9K Followers 2K Following
Romeo @3f_romeo
519 Followers 805 Following Co-Founder @3f_xyz, Former HedgeMonkey @ Abraxas Capital
anton carlo @antoncarlo5
28 Followers 156 Following NextBlock Founder Insurance and Reinsurance Broker Helpet Co-Founder
Krisztian Sandor @sndr_krisztian
5K Followers 2K Following stablecoin, tokenization, RWA enjoyoor @CoinDesk | bylines @Reuters @Forbes @Forbes_HU | fulbright alum @nyuniversity | made in Hungary
Blockchain Associatio... @BlockchainAssn
47K Followers 894 Following The unified voice of the crypto industry. The industry is hiring. https://t.co/deyJKqOBJF
Dinari @DinariGlobal
109K Followers 98 Following Over 230 1:1 backed tokenized stocks, ETFs & more with dividends. US-based SEC transfer agent. Available on 5+ chains & via API.
Alpha.rwa | Adi @alphacyl
10K Followers 4K Following RWA Growth Operator| RWA/Defi research | | @dEURO_com | prev : @shapeShift @AISUEDE | @ADIChain_
Tether @tether
569K Followers 246 Following Finance | Power | Data | Edu | Evo - Empowering Individuals, Communities, Cities, & Nations - Unstoppable Together | https://t.co/uYJ5YbfDFU | https://t.co/DvCYi4ZTMP $USDt
Real-World Asset Summ... @rwasummit
4K Followers 1 Following The original, invite-only event for the most influential leaders in the tokenized asset industry.
T-REX Network @trex_network
21K Followers 261 Following Compliance and Identity infrastructure for tokenized securities. 🦖 Built on ERC-3643. Backed by Apex Group.
ETHRA INVEST @ETHRAINVEST
12K Followers 20 Following Ethra Invest is a leading investment and private equity firm specializing in creating value through strategic investments in diverse industries.
Ethra Ship @EthraShip
107K Followers 44 Following The ocean economy meets onchain yield. Sea Verity verifies key maritime intelligence. Ethra Harbor is the participation layer. Backed by @ETHRAINVEST.
jesse.base.eth @jessepollak
360K Followers 5K Following @base builder #001 | send your agent https://t.co/cEy8Ih50qK to get building
Robert Leshner @rleshner
2.1M Followers 2K Following CEO @superstateinc, Investor @robotventures, prev founded Compound; ardent capitalist; tweets are typically satire

3x Capital @capital_3x
4K Followers 688 Following Investment firm partnering with founders from idea to scale.
Multicoin Capital @multicoin
1.4M Followers 0 Following Thesis-driven investment firm that invests in tokens and blockchain companies. ***This account does not tweet and never has.***
WALLY the RWA Elephan... @WALLY_DAO
3K Followers 671 Following The dedicated decentralized community for Real World Assets. Whitepaper available at https://t.co/OkHkIjnbxz 🐘🐘🐘
RWA Foundation @RWAFoundation_
25K Followers 368 Following Onboarding 1 billion people into RWAs 🐘🕶️ Manager of the @Wally_DAO
RWA Llama 🦙 @RwaLlama
852 Followers 375 Following Turning real-world assets into unreal-world yields. Threads on tokenization, DeFi rails, trillions getting onchain. NFA 🦙 🔎Trends for United States
You might like


















