

Shubham | SEBI RA @ShubInvests
SEBI RA (INH000016913) - Long-term investor in Small, Mid and Micro Caps | 7+ years of Experience in Stock Mark | Fundamentals over FOMO 🔍 shubinvests.com Joined July 2024-
Tweets388
-
Followers116
-
Following32
-
Likes8
@Aditya_Hujband Many many congratulations Bro ! ❤️👏 5K is just the beginning, many more milestones to come. Keep growing and inspiring! 🚀📈
🏛️ THE MOST INTERESTING PART OF THE NSE IPO ISN’T THE IPO. Think about this: You trade on NSE. Your broker connects to NSE. Your mutual fund trades through the market. Nifty is an NSE product. F&O activity happens on NSE. Now the exchange itself is coming to the public market. IPO: ₹22,561 Cr | ₹1,700–₹1,785 But here's the twist: 👉 NSE gets ZERO fresh capital. It is a 100% OFS. Existing shareholders are selling. So you're not funding NSE's growth. You're buying a piece of an already extremely profitable market infrastructure business. And the numbers explain why investors are interested: 📊 92.99% cash-market share 📊 99.79% equity-futures share 💰 FY26 PAT: ₹10,302 Cr 📈 PAT margin: ~55% 📈 ROE: 33.21% 📈 ROCE: 42.80% Valuation: ~43x P/E. That's NOT cheap. But here's my question: **Would you rather buy a ₹4.4 lakh crore monopoly-like franchise at 43x earnings… or a cheaper company with much weaker competitive advantages?** Because IPO investing isn't about: ❌ “Is NSE expensive?” It's about: ✅ “Is NSE expensive relative to the quality and durability of its earnings?” And there is another interesting angle: Several listed institutions already own NSE shares. The IPO could potentially make those hidden holdings more visible to the market. I like the business more than I like the valuation. Now I want your honest answer: Would you apply for NSE at ₹1,785? 👇 YES — Quality justifies the premium or NO — 43x P/E is too expensive Comment YES / NO + WHY. Let's see where the market stands before the IPO opens.

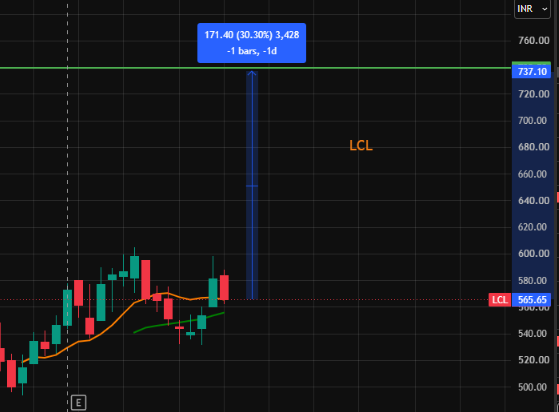
Lohia Corp: Is the market underestimating the earnings story? A machinery company with ~40.7% India market share and ~15.4% global share is showing a sharp fundamental improvement. ₹1,778 Cr order book, Revenue +59.7% YoY, EBITDA +167.7% , PAT +292.3%, EBITDA margin ~20%, ROCE 52.3% , Debt down to ₹48 Cr The interesting part isn't just the growth. It's the combination of market position + order visibility + margin expansion + cash generation + improving balance sheet. At the report's CMP of ₹565.50, the valuation also raises an important question: has the market already priced in the improvement, or is it still underestimating the company's potential earnings base? But the thesis needs to be tested. Can 20% margins sustain? Can the ₹1,778 Cr order book convert into revenue and cash? Can Lohia defend its moat against cheaper Chinese competitors? Can recycling and after-market revenue become meaningful growth engines? And don't ignore the risks: low liquidity, capital-goods cyclicality, margin normalisation, plastic-packaging disruption, Chinese competition, recycling execution and governance information that still requires verification. For me, this is not simply a “buy” story. It is a company worth watching quarter after quarter and testing against the numbers. Research > narrative. Evidence > excitement. #LohiaCorp #StockMarket #IndianStocks #FundamentalAnalysis
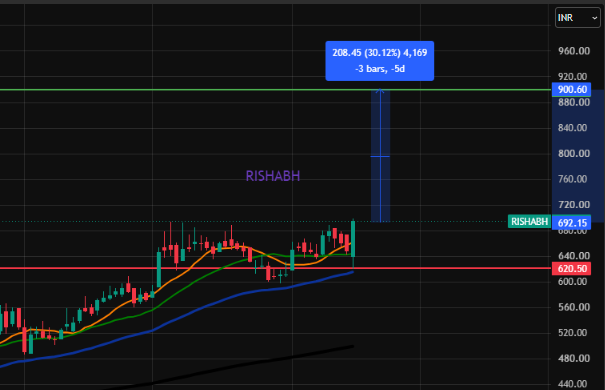
Rishabh Instruments: ₹692 → ₹796 📈 ~15% up since my original post. I wrote about the company when it was at ₹692. Today: ₹796 | +8% today. 🚀 This is exactly why I focus on research before the price moves. The thesis remains the same understand the business, identify the moat, track the numbers, and let the market do its job. Research first. Price later. 📊
🏰 WHY IS RISHABH INSTRUMENTS INTERESTING? Forget the stock price for a moment. What would it take to build Rishabh's business from scratch today? 🤔 ⏳ 40+ years of manufacturing experience 🌍 Presence across 100+ countries 🏭 5 manufacturing facilities 🔬 7 R&D centres 📜
Crude: “Hello, I’m back.” Brent: ~$95+ US-Iran tensions: “Hold my portfolio.” Market opened like it had seen the electricity bill... Then recovered from the lows and closed near 23,914. Meanwhile investors: Morning: “Buy the dip!” Afternoon: “Which dip?” Closing bell: “Maybe tomorrow.” And somewhere in the market, Coal India was sitting there like: “Everyone worried about oil? I’ll take the spotlight.” Lesson of the day: In markets, sometimes the biggest risk isn’t your stock. It’s something happening thousands of kilometres away that suddenly decides your stock should have a bad day. #Nifty50 #StockMarket #IndianStockMarket #Investing #DalalStreet #Markets #Nifty500

🚨 What if the future of cancer treatment is NOT one drug for millions of people ? But millions of different drugs one for each patient. Moderna & Merck are testing a personalised cancer vaccine that starts with the patient’s own tumour. Here’s the fascinating part: → Sequence the tumour → Find its unique mutations → Select potential cancer targets → Encode them into mRNA → Manufacture a personalised dose The manufacturing challenge completely changes. Traditional pharma = make millions of identical doses. Personalised medicine = make millions of different doses using the same process. And this could be a BIG opportunity for India. India already has strengths in pharma manufacturing, generics and cost efficiency. The next opportunity may not be: “Can India make the same medicine cheaper?” It could be: “Can India make personalised medicine cheaper?” That is a much bigger question. The future of pharma may be about scaling personalisation, not just production. What do you think could India become a global hub for personalised medicine ?
Another day at NSE. Not just standing beside the bull, but remembering what it represents conviction, discipline, patience, and the courage to stay in the game. The market will test all four. #NSE #StockMarket #Investing
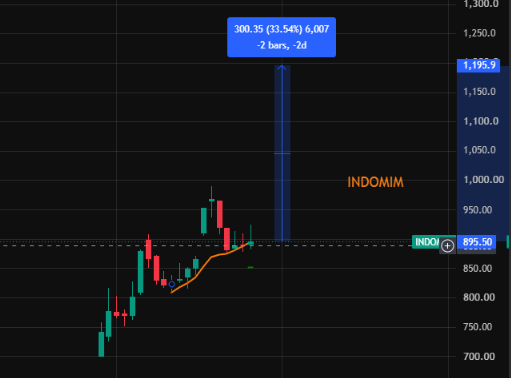
🔩 Indo-MIM : A niche manufacturing moat worth watching Indo-MIM operates in Metal Injection Moulding (MIM), a highly specialized process used to manufacture complex precision components for automotive, aerospace, medical, electronics and other high-value applications. The key attraction is scale + specialization. Indo-MIM is one of the largest MIM manufacturers globally, creating a meaningful barrier to entry. 📌 What stands out: • FY26 OCF: ₹1,077 Cr vs ₹533 Cr net profit ~2x cash conversion • FY26 FCF: ₹659 Cr after years of heavy capex • ROCE: 27.74% | ROE: 21.26% • D/E: 0.56x • Interest coverage: 12.24x • Promoter holding: 93.34% The business appears to have moved from a capex-heavy phase toward stronger cash generation. ⚠️ But there are important caveats: limited public disclosures, no 5-year ROCE/ROE trend available, and the reported 889% YoY Q1 revenue growth needs base-effect context. At a ₹44,000 Cr market cap, Indo-MIM is no longer an under-the-radar small-cap story. Strong business + niche global positioning + improving cash generation. Valuation and future growth execution now matter. Not a buy/sell recommendation. DYOR.
One of the stocks I picked early in my journey #cupid became more than just a return. It was one of the moments that reminded me why I chose research. From my early corporate experience to becoming a SEBI Registered Research Analyst, the biggest lesson has been simple: know what you’re looking for before you start looking at the numbers. My research, conviction and patience in CUPID delivered ~1,475% returns from my chosen entry. The return is exciting, but the journey behind that conviction means more. 📈 Still learning. Still researching. Still building. This is just one chapter of my journey as a SEBI RA. 🚀 Not a recommendation. Past performance is not indicative of future returns.

🏰 WHY IS RISHABH INSTRUMENTS INTERESTING? Forget the stock price for a moment. What would it take to build Rishabh's business from scratch today? 🤔 ⏳ 40+ years of manufacturing experience 🌍 Presence across 100+ countries 🏭 5 manufacturing facilities 🔬 7 R&D centres 📜 Global certifications 🇪🇺 European presence through Lumel 🤝 Established industrial customers And the numbers are getting interesting: 📈 FY26 Revenue: ₹267.6 Cr 💰 EBITDA: ₹60.4 Cr 🔥 EBITDA Margin: 22.6% 📊 PAT: ₹41.7 Cr But here's the interesting part: A competitor can copy a product. Can it copy 40 years of manufacturing know-how, certifications, customer relationships, R&D and global distribution? That's where the moat starts. 🏰 🚀 What I’m watching next: • Can revenue growth remain strong? • Can ~20%+ EBITDA margins sustain? • Can ROCE/ROE continue recovering? • Can US + Europe become bigger growth engines? • Can new products create the next leg of growth? 💡 My takeaway: The biggest competitive advantage may not be what Rishabh sells today but the ecosystem it has built to keep selling globally tomorrow. Would you call this a genuine moat, or simply a good manufacturing business? 👇 #RishabhInstruments #SmallCap #Manufacturing #Electrical #Investing
🚨 Omnitech Engineering Ltd (OMNI) @ ₹579 — Potential Multibagger? Sometimes the interesting part isn't the stock price. It's what the company is quietly building behind it. OMNI has a ₹3,000+ Cr order book, 256+ global customers, 5-micron precision capabilities and exposure to Aerospace ✈️, Energy ⚡, Automation ⚙️ & China+1 🇮🇳. Q1 FY27 revenue grew ~65% YoY, while profit jumped ~468%. EBITDA margins are above 30%. But the real story is ahead: Can OMNI convert its order book into revenue, revenue into cash, reduce debt and compound earnings for years? 👀 That's why I see potential multibagger characteristics — not because OMNI is cheap, but because the business could become much larger. ⚠️ P/E ~70x | D/E ~2.2x | FY25 OCF negative. The next few quarters will matter more than the last one. Educational research only. Not investment advice. #OMNI #Multibagger #SmallCap #IndianStocks

SEBI’s SME Listing Overhaul: A Necessary Reset? SEBI is reportedly considering a significant overhaul of the SME listing framework, with tighter eligibility, greater transparency and stronger safeguards against price manipulation. From an investor’s perspective, this is an important development. The SME segment can give promising businesses access to public capital at an early stage. But the same segment can also carry higher liquidity, valuation and price manipulation risks. The real challenge is finding the right balance: Stricter enough to protect investors. Flexible enough to support genuine entrepreneurs. For me, the key question is not whether SME regulations should become stricter. It is: Can SEBI design a framework where genuine businesses get capital, while speculative activity becomes harder? What would you prioritise in the new SME framework? 1. Stronger eligibility criteria 2. Better disclosure requirements 3. Stricter promoter/investor safeguards 4. Greater surveillance of price & volume activity
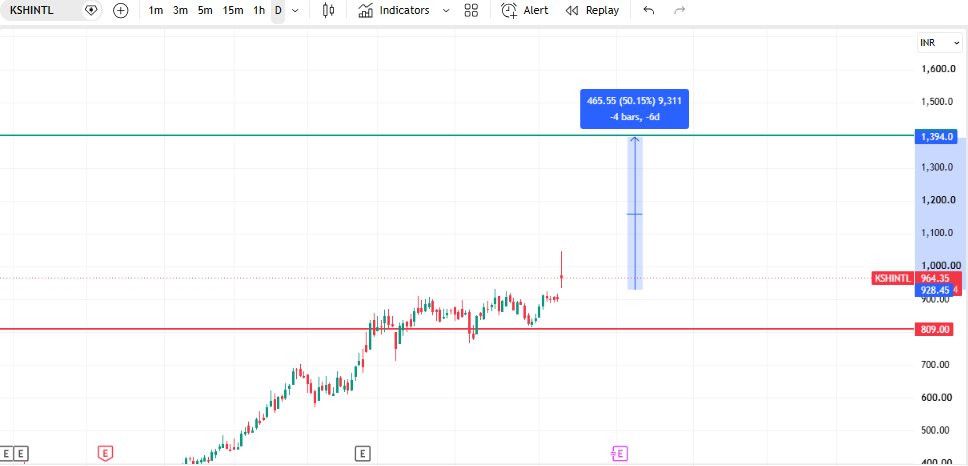
KSH International: Strong FY26, Bigger Growth Plans $KSHINTL is emerging as an interesting play on India’s power T&D, renewable energy and transformer capex cycle.📊 FY26 Performance • Revenue: ₹3,107 Cr | +61% YoY • PAT: ₹110 Cr | +62% YoY • EBITDA: ₹190 Cr • EBITDA/ton: ₹67,600 • Debt/EBITDA: 0.39x vs 1.21x🔥 Q4 FY26 • Revenue: ₹1,018 Cr | +101% YoY • PAT: ₹34.5 Cr | +87% YoY • EBITDA/ton: ₹74,000🏗️ Future Plans • Capacity: 43,445 MT → ~59,000 MT by FY27 • Additional ~10,000 MT potential capacity • PEEK insulated wires for 800V EV traction motors • Green copper backward integration targeted for H2 FY27 • Export contribution targeted toward ~40%⚡ With ~75% revenue from specialized wires, KSH is positioned in CTC and other high-value winding wire applications across transformers, T&D, renewables and data centres. ⚠️ Key risks: Customer concentration, supplier concentration, power-sector dependence and product concentration remain important factors to monitor.
🚀 AZAD ENGINEERING - A STORY BEYOND NUMBERS What if the next big manufacturing story is hiding inside the engines that power aircraft, turbines and defence systems? ✈️⚡🛡️ That is where Azad Engineering enters the picture. The company manufactures highly specialised precision components used in aerospace, defence, energy and oil & gas, supplying global giants such as GE Vernova, Siemens Energy, Mitsubishi Heavy Industries, Rolls-Royce, Honeywell, Boeing and HAL. But the interesting part is what is happening behind the scenes. 📦 ₹6,500 Cr order book gives the business significant revenue visibility. ✈️ Aerospace & Defence is accelerating, with FY25 revenue growth of around 84%, much faster than its traditional Energy & Oil & Gas business. 🏭 Capacity is expanding aggressively, with dedicated facilities for major customers and a new manufacturing facility planned at Tuniki Bollaram, Hyderabad. 💰 The company has also raised ₹700 Cr through QIP, with a major portion directed toward machinery, equipment and automation. The bigger opportunity is the combination of India's defence push + global aviation demand + power generation + precision manufacturing. But every growth story has another side. ⚠️ Working capital remains high. ⚠️ Expansion brings execution risk. ⚠️ Capacity utilisation needs to improve. ⚠️ Order-book conversion will be critical. So the real question isn't simply “How big is the order book?” The real question is: Can Azad convert this order book into sustainable revenue, profits and cash flow? That is the story worth watching. 👀 Azad Engineering from precision components to a potential global engineering platform.

🚀 Freshara Agro Exports Research Update I researched Freshara at ₹164 in Feb 2025. 📈 CMP now: ~₹361 🔥 Gain from research price: ~120%
🚀 Freshara Agro Exports Ltd: A Small-Cap with Global Ambitions! 🔹 CMP: ₹164 | MCap: ₹385 Cr | P/E: 41.2 🔹 Strong Export Play – Serving global markets with preserved gherkins & pickled veggies. 🌱 🔹 High Promoter Holding – 62.58% confidence in business! 💪

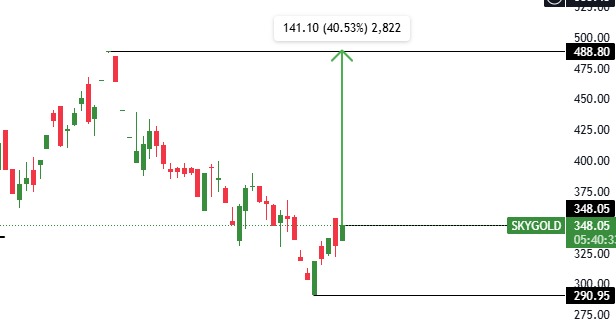
🚨 Sky Gold & Diamonds The Story Has Changed! Back in Feb 2025, we highlighted SKYGOLD at ₹348 with a ₹488 target. Today, the stock is around ₹800 more than 2X from that level.
🚀 Skygold (NSE: SKYGOLD) in the spotlight! 🎯 CMP: ₹348 | Target: ₹488 (45 days) 🔻 Stoploss: ₹290 🏆 B2B supplier to Malabar, Joyalukkas, Kalyan & more 🤝 New tie-up with Aditya Birla for jewellery venture

Aakanksha Gupta_ @ElisaCuster
88 Followers 919 Following SEBI Registered RA | SEBI Reg. No - INH000013457 | Profitable Trader 📈| Investor| Engineer| Mentor| Telegram-https://t.co/71CKwjPEaW| 📞9324404610
Karthik R @KarthikRvr
1 Followers 34 Following
A Digital Bioogger @Andeerzeira
98 Followers 905 Following Aseem Juneja. Founder - Stock Pathshala, ADB. Author, Book - Fraud Free. MBA CEIBS Shanghai. YouTube since 2016, 1.2M Community. Ex- Infosys, Angel One, IBM
A Digital_Bloggerr @CamiloRivera14
58 Followers 547 Following Aseem Juneja. Founder - Stock Pathshala, ADB. Author, Book - Fraud Free. MBA CEIBS Shanghai. YouTube since 2016, 1.2M Community. Ex- Infosys, Angel One, IBM
Seb @Sebmoo0
9 Followers 45 Following
Digital Bloggar🇮�... @HS26031205
49 Followers 652 Following Aseem Juneja. Founder - Stock Pathshala, ADB. Author, Book - Fraud Free. MBA CEIBS Shanghai. YouTube since 2016, 1.2M Community. Ex- Infosys, Angel One, IBM
Sneeha S @billbo_6
41 Followers 492 Following Ex-Qualcomm . Ex-IBM . Investor & Swing Trader 📈 . Building AI-powered products to automate Stock Market TechnoFunda & Business Analysis . Fitness Enthusiast
Ram Taelugu Tradar @calebsamuel73
108 Followers 422 Following 📈 Swing Trading & Investing 💡 Learning & Sharing 🤖 AI Learner 🚫 No Tips • No F&O • Education Only
Raan Telugu Trader @Ronjone38562750
111 Followers 633 Following 📈 Swing Trading & Investing 💡 Learning & Sharing 🤖 AI Learner 🚫 No Tips • No F&O • Education Only
vikash meena @vicky_meena26
18 Followers 302 Following
Parag Mehta @paragaquarius
26 Followers 679 Following If you are living your #life without giving a 'F', you are only living a LI[ ]E
TradeSet - Software f... @tradesetra
13 Followers 178 Following Tradeset is a powerful platform built exclusively for SEBI-registered Research Analysts (RA).
P Karthikeyan @Karthik14158027
110 Followers 2K Following

Suhani Sharma @suhanisharma125
14K Followers 12K Following Passionate Trader || wanderlust 🏖️ || Posts shared = No Recommendation || Sebi Unregistered ||CFA Level 1 ||
Parveen Sharma @parveenrajs
7 Followers 140 Following
Gujjubhai @Drkaran13
23 Followers 162 Following
Mahavir @Mahavir077
1 Followers 450 Following
Anupam Awasthi @AnupamAwasthi47
222 Followers 3K Following
TheBigBear🃏 @TheBigBearHQ
2K Followers 2K Following Fishing for bearish trades and bullish investments. 🇮🇳 Gandhi ❌, Nehru ❌ and Ambedkar ❌ || Subhas Chandra Bose 🫡🫡
Raj Sharma @rajsharmatt
421 Followers 627 Following SEBI Registered Research Analyst | Reg. No. INH000029236 | Founder @KuberResearch | Independent Equity Research & Market Insights.

FloraOrlando @qPl0bj55gF9ixi6
205 Followers 6K Following Nurse by profession | Meme curator by passion 🩺😂
prince @adeshyadav40864
25 Followers 388 Following
Babu George @BGeorge2050
109 Followers 3K Following Seasoned HR Professional. Student of Equity Investing.
Alice @3Glwhc3JsNDDo7
186 Followers 6K Following
Vinod @HassijaVinod
168 Followers 7K Following

CA Kaustav Majumdar @KustavMaj94587
3 Followers 30 Following Chartered Accountant. Ex UBS AG, Citibank & American Express. Nothing is a Reco. I am wrong several times. Only for education purpose. Connect, Learn, Grow.
Amit Agarwali @ShankarGameti7
13 Followers 115 Following Investor, Learner, Listener, Invest in Businesses having Value+Growth+Quality Management+Sound Balance Sheet. Like Cyclical & Turnaround Stocks.
RA Aditya Hujband (SE... @Aditya_Hujband
6K Followers 2K Following SEBI Reg. Research Analyst (INH000011185). BSE Enlist No. 5709 | Investment Advisor (Level 1 & 2) 🎓| MBA Finance 💼 | Ex-CA Final Aspirant (BAA - ICAI)
Pradum Brijpuria @Pradum0911
71 Followers 510 Following
Bimal Sahoo @BIMAL_BKS
65 Followers 455 Following
Ramesh Pal SEBI Regis... @Dehradunbulls
1 Followers 9 Following SEBI Registered Research Analyst (INH000021395) | Stocks | Charts | OPTIONS | Price Action | Intraday Trading | Investing | IPO | MBA in Finance | MA ECONOMICS
CamilleWallis @58qnG8Uyl2efT2
17 Followers 1K Following
Dr.Ramesh Gohil @rameshgohil
174 Followers 2K Following
Brad Jose @bradjoseballer
319 Followers 2K Following Are you being targeted? Gangstalked and tortured this is your period of healing both spiritually and mentally you can get free of torture,Send me direct message
shubham runthla @shubham_runthla
421 Followers 1K Following
Shamim @Shamim752919510
5 Followers 27 Following
Shashi Prakash Yadav @PrakashSha6127
15 Followers 155 Following
RaJa Nagarajan @ranag5395
39 Followers 1K Following Governance, Autophile, Environmentalist, Audiophile, Avid learner & Tech enthusiast
Kartik @3Kastrostocks
46 Followers 285 Following Astrologer | Stocks Enthusiast | Value investor | Swing trader | Not a SEBI registered advisor | Share Stocks For Educational Purposes

DEV NEWAR @NewarDev12712
4 Followers 250 Following whatever is happening to you has been waiting to happened since the beginning of time
Krishna bhanu @mvbm31
297 Followers 3K Following Hardworking Chemical Engineer with MBA, Lean Six Sigma Black Belt,Certified Hazop leader, Analysis,identifying and capturing opportunities safely. make team win


Laxman Jat @vadvala36173
123 Followers 1K Following
Yogesha Kumar Yogesh @Sonas1996Kumar
7 Followers 70 Following
SEDHU MADHAVAN @sedhumadhavan81
274 Followers 107 Following Angel Investor | SEBI Registered Investment Advisor If you can’t explain it to a six-year-old, you don’t understand it yourself.”
Aakanksha Gupta @aakankshalovely
178K Followers 30 Following SEBI Registered RA | SEBI Reg. No - INH000013457 | Profitable Trader 📈| Investor| Engineer| Mentor| Telegram-https://t.co/h3PZk37IF7| 📞9324404610

A Digital Blogger @adigitalblogger
21K Followers 29 Following Aseem Juneja. Founder - Stock Pathshala, ADB. Author, Book - Fraud Free. MBA CEIBS Shanghai. YouTube since 2016, 1.2M Community. Ex- Infosys, Angel One, IBM
Ram Telugu Trader @RamTeluguTrader
7K Followers 2K Following 📈 Swing Trading & Investing 💡 Learning & Sharing 🤖 AI Learner 🚫 No Tips • No F&O • Education Only
fuzz AI @ask_fuzz
2K Followers 11 Following The only AI you need for financial and equity research - powered by artham, India's very own SLM. 🇮🇳
Intrinsic Compounding @soicfinance
287K Followers 454 Following 🏛Seeking Wisdom in the Indian Stock Markets|Disclaimer:Nothing should be considered as investment advice to buy or sell| Education|Fundamental Analysis

Abishek K V - SEBI RA @Akveq_
38K Followers 160 Following Pro Trader || Analyst || On a mission to educate retail traders || SEBI registered RA INH000022066 || BSE: 6652 || Telegram: https://t.co/Ph8Zbyg83T
DIXIT AGGARWAL @Dixitagg
10K Followers 477 Following NISM RESEARCH ANALYST CERTIFIED. Sailor by profession, Investor by Vision. Inspired by Fitness .Tesla. Bitcoin . Indian/US Equities. AI is the future .
_KadamSumit_ @_KadamSumit_
13 Followers 29 Following
RA Aditya Hujband (SE... @Aditya_Hujband
6K Followers 2K Following SEBI Reg. Research Analyst (INH000011185). BSE Enlist No. 5709 | Investment Advisor (Level 1 & 2) 🎓| MBA Finance 💼 | Ex-CA Final Aspirant (BAA - ICAI)
Ramesh Pal SEBI Regis... @Dehradunbulls
1 Followers 9 Following SEBI Registered Research Analyst (INH000021395) | Stocks | Charts | OPTIONS | Price Action | Intraday Trading | Investing | IPO | MBA in Finance | MA ECONOMICS
SecuritiesandExchange... @SEBI_updates
19K Followers 0 Following to protect the interests of investors in securities and to promote the development of, and to regulate the securities market..Disclaimer:https://t.co/QK53sWAMQS
StockGro @stockgro
362K Followers 2 Following India’s Leading Stock Market Advisory & Research Platform 35M+ users | 150+ SEBI Regd. analysts | AI-powered by Stoxo Daily trade ideas with entry, exit & stop
T FOR TRADER SEBI REG... @tfortraderRA
28 Followers 143 Following Investor | Trader | Mentor SEBI RA- INH000020059 BSE Enlistment No- 6522 Contact Number- 6260834008
CA Tarun Nagpal @compliancify
177 Followers 315 Following 15+ yrs exp// CA, LLb, https://t.co/cAWKnwdyJZ SEBI regulations, Corporate law & Labour law// Legal consultant // Simplifying compliance // Contract & drafting experts
ARRAI- Assoc. of Regd... @ARRAI_SEBIRA
958 Followers 0 Following Association of Registered Research Analysts of India (SEBI recognized) Join for membership at https://t.co/8xMRFX7ILH
M.J Research SEBI Reg... @mjresearchs
39 Followers 30 Following M. J Research, SEBI Registered Research Analyst. Provide short term trading calls based on technical and fundamental analysis. F&O Contra Hedging Data Investing
Vipin Sharma @vipin239
34 Followers 68 Following SEBI Registered Research Analyst, (NISM:X-A,NISM:X-B,NISM:XV) Certified, I give buy/sell recommendation in stock market 📊📈📉
Mehul Jiyani @jiyani02
7K Followers 942 Following SEBI Registered Research Analyst I Founder -TradersCafe I Option Writer I Talks about trading and stock market
CMA Kr Siddhartha Sin... @cmasids
38 Followers 116 Following Research Analyst (SEBI Regd. Registration NO INH000017310 Air veteran, full time trader, investor, youtuber, and Cost Accountant.
Yash Shrivastav @Yashsince1995
616 Followers 20 Following 📍Delhi 🇮🇳 → Global Markets 🌍 📊 Former SEBI Registered Research Analyst 📈 Nifty | Stocks | Forex | Crypto 🚫 No Tips | View
Gaurav Puri @GauravPuriGP
136 Followers 32 Following SEBI Registered RA (Reg No: INH000014605) | NISM Certified | MBA | B-Tech https://t.co/Dw9N9z0Gal
Vivek Bansal @VivekBansal23
56 Followers 130 Following Equity Investor & Trader. More than 17 years in Stock Markets. Multibagger hunting, Wealth Creation. Tweets for education purpose only
PROFIT X RESEARCH @ProfitXResearch
217 Followers 51 Following Over 25 years in the Markets ,SEBI Registered Research Analyst INH000014508 MBA -Finance and Banking (Authored 20+ books ) https://t.co/FMJ5atuvfU

Amit Jain @Intelisytrading
2K Followers 29 Following .SEBI Regd RA Since 2017🇮🇳📈📉 .Josh Talk Speaker 🔊 22+ Yrs of Experience 🏅 .Guided 2 Lakhs+Traders .Helping u Earn Thru Stock Market 💎
Hasif @hasif_the_i_way
484 Followers 270 Following Founder & CEO- @RichesseConsult - SEBI Registered Research Entity SEBI Regn. No. INH000012704 | Value Investing | Opportunistic Investing | Cricket
Shree Ram Raut @FinTaxCoach
11K Followers 471 Following CA | SEBI RA (INH000012537)| Trend Follower-Buy Over Bought, Sell Over Sold | Wealth, Investing, Business & Tax | Ex-Deloitte
Patekar Shubham || Mi... @microbetsindia
17K Followers 414 Following 25 •• Investing in high-growth microcap companies before they get hot & famous🐣
Finding stocks | च�... @chndn_r
90 Followers 163 Following Engineer, Learner, Finding swing opportunities, not sebi registered.You might like


















