
cryptyonics @vranadee
Apunich bhagwaan hai India Joined May 2021-
Tweets248
-
Followers6
-
Following186
-
Likes206

#WATCH | Delhi: Malaysia’s Prime Minister Anwar Ibrahim sings a popular Hindi song “Khwab Ho Tum Ya Koi Haqeeqat” in Delhi. (Video source: Anwar Ibrahim/X) #BRICSSummit

✨ Ganesh Chaturthi Special Offer ✨ This Ganesh Chaturthi (27th August) is the most auspicious day to wear your Abhimantrit Gomti Chakra Bracelet – a powerful symbol of prosperity, protection, and positivity. remedyideas.graphy.com/products/Abhim…

Union Home Minister Amit Shah tweets "Nation salutes the unparalleled valour of our Armed Forces – the destroyers of our enemies and the shield of Bharat. We also salute our first line of defence, the courageous personnel of the BSF. The bravery of our forces will forever be etched in our glorious history. I congratulate PM Modi for his exemplary leadership in delivering justice to the departed souls of our innocent brothers. Time and again, PM Modi has proven that no enemy of Bharat can go unpunished."


भारत माता की जय!
@DGPMaharashtra is there any way to keep restrictions on IVR calls made by random organizations like Bajaj Finance or Home Tathastu Realator or Rajeha Realtor etc…? @CMOMaharashtra @Navimumpolice
@PanvelCorp @MMVD_RTO नो पार्किंग मधल्या गाड्या उचलतात पण अवैध रित्या अतिक्रमण आणि बेक़ायदा रित्यापथक्रमण करनारे फेरीवाले दिसत नाहीं हयाला काय महान्यचे
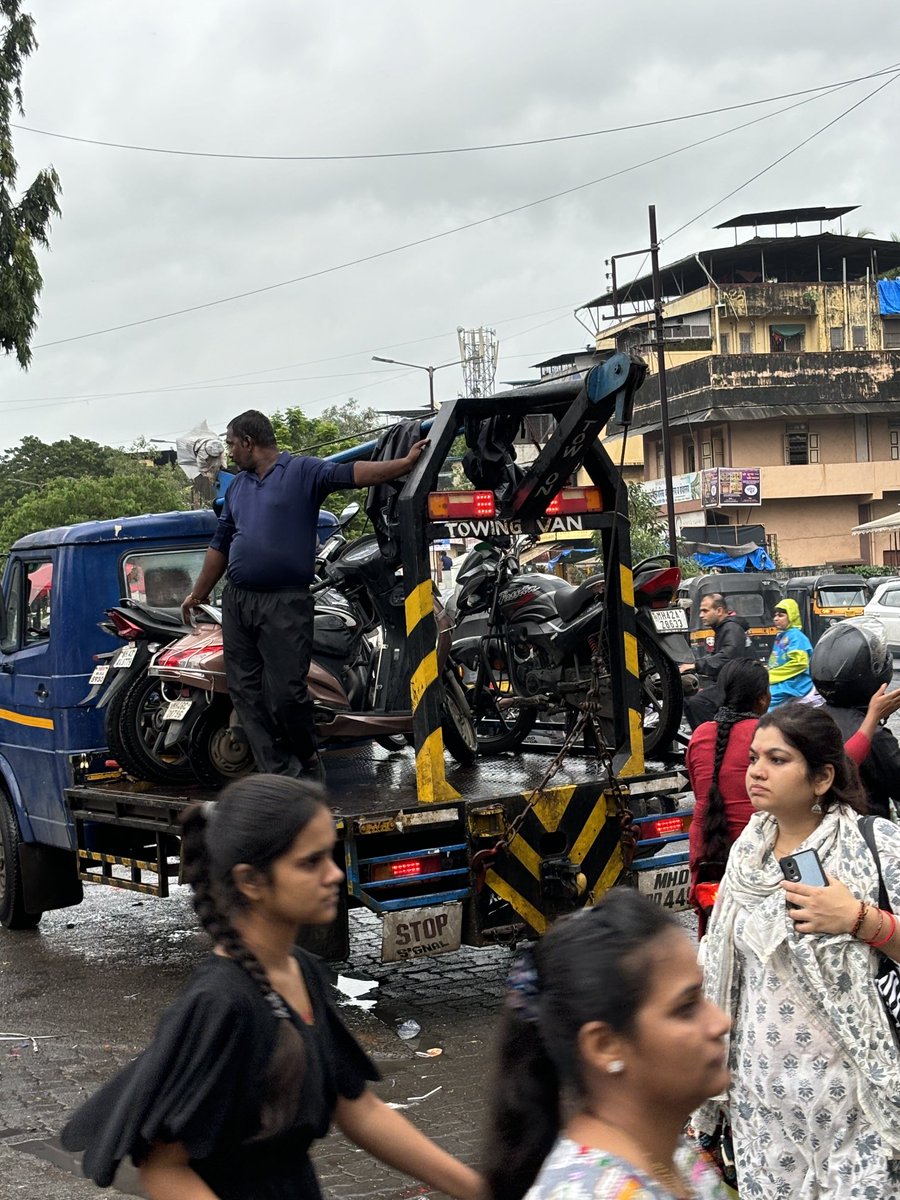

मुंबई - गोवा महामार्ग दयनीय अवस्था... मा. नितीनजी गडकरी साहेब यांना तळमळीचे आवाहन....
‘3 एकर खडकाळ जमिनीत 30 लाखांची खजूर शेती केली’ - मराठवाड्यातल्या शेतकऱ्याची कमाल #farming #successstory #marathwada @shrikantbangale @dhananjay_munde @InfoJalna
@ithakurprashant Panvel water problem: When it will get resolved..?
Seems fair to me.

BIG NEWS 🚨 Guyanese President openly exposes BBC journalist. Video goes viral 🔥 ⚡ BBC Journalist : "So, Do you have the right to release all of this carbon?" Guyanese President 🔥🔥 : "Do you the right to lecture us on climate change? Do you know that Guyana has a forest forever that is the size of England and Scotland combined? Our country is saving forests."


Finally entire B,lore migrated to cloud #AWS
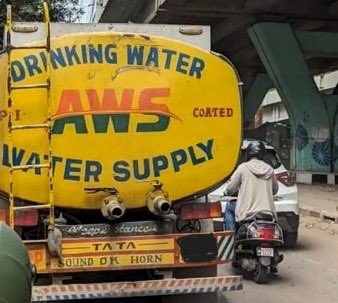
@Darshanj101 i was trying to connect with you but I am not getting your cell phone number at all. Could you please DM me your number
@TimesAlgebraIND I think NIFTY will be 24-400 on that day … 😛
@abidsensibull Bhagwaan ka shukra hai ki sagar ka ek dialogue hamesha yaad rehta hai… paise bachake tread kare … shayad isiliye paise bach gaye 😝
@swatip3844 @AnilSinghvi_ @AngelOne @DhanHQ @zerodha Market ko kaisa lagta hai woh important hai… but you may see 22-January ko 220124 figure… Jai Shriram ❤️

The Yearly Cycle : 24th Jan 2023 - Hindenburg - Adani report came out 25th Jan 2023 - we saw the reaction to the same . 26th Jan 2023 - Bottom made 25th it formed a small top and price could not sustain above it for a few weeks Anniversary date next week +/- 1 day Lets see if we make a small top or bottom by then . This Top / bottom becomes a Key support / resistance area for the market . Every year we see a trigger 1 -2 days before / After the dates followed by repeated cycles . Part 1 #nifty
Scenario 1 – Go for Home Loan Maximum Tenure Are you planning to take a home loan? It's common to go for a shorter tenure to pay less interest and complete the loan sooner. However, our suggestion is to opt for the maximum tenure you are eligible for and invest the difference in mutual funds through SIP. For instance, if you opt for a 25-year loan instead of a 20-year loan, you can save up to Rs. 3000 per month. By investing this amount in mutual funds, after 20 years, you can pay off the remaining 5 years of your loan and receive around 50 Lakhs. While past returns and the future economy are not guaranteed, we believe this is a highly possible outcome based on the assumption of a 15% return. So, before taking a home loan, consider the benefits of a longer tenure and investing the difference in mutual funds. Scenario 2 – Go for Home Loan Minimum Down Payment Are you planning to buy a house? Make sure you go for the minimum down payment. Many people tend to go for a higher down payment to reduce their home loan EMI. However, this is not the right approach. If your home loan is 1 crore and the minimum down payment is 20 lakhs, then the total EMI works out to be 1.72 crore. By putting another 20 lakhs, the total EMI works out to be 1.3 crore, which helps to save 43 lakhs in the future. But, instead of giving the money to the home loan provider, if you invest the same 20 lakhs in Mutual Funds for 20 years, it would be around 3.27 crore at the rate of 15% CAGR. By deducting 1.3 crore from 3.27 crore, you are making around 1.97 crore, which is a huge amount. Even if you have 2 crores ready cash, it is always better to go for home loans so that you can make more money than giving it in cash. This is a practical approach. Remember, go for the minimum down payment and invest the rest for a brighter future. Scenario 3 – Do not Pre-pay Home Loan, stay till the End Are you considering prepaying your home loan to come out of debt early? Think twice before you do so. As there is no commonality when it comes to prepaying, it is difficult to explain in detail. However, let's take the example of someone who decides to prepay after 10 years when the home loan tenure is 20 years. After 10 years, the principal outstanding is 35.32 Lakhs. This means they have paid only 14.68 lakhs towards the principal and the interest component alone is 39.31 Lakhs. For the next 10 years, the interest outflow on the remaining principal amount of 35.32 Lakhs is only 18.65 Lakhs. Although the comfort level of paying a 45K EMI may be difficult today, it won't be as much of a burden 10 years from now. So, why prepay after paying so much towards interest in the first 10 years? This decision is often emotional, and unfortunately, many people fall into this trap. Remember, holding onto your EMI payments until the committed tenure can be a wise financial decision. Assumption: Mutual Fund Returns over the next 20 Years 15% CAGR. Conclusion: Most of them do opposite of what I am suggesting in all the 3 scenarios, if not at least one. This strategy is only for those who are not emotional and practical. Others I am sure will post bad comments, it shows their emotionally aligned, its okay. Disclaimer: Please note that investing in mutual funds carries market risks. It is important to carefully read all scheme-related documents before making any investment decisions. The information contained in the reports is intended for informational purposes only and should be used solely by the recipient. While we have taken great care in compiling the data and contents of this report, we make no representations about the reasonableness of the assumptions or accuracy of any data. Any decisions made based on this information are the sole responsibility of the recipient. We reserve the right to correct any errors or discrepancies in the reports if they are observed or brought to our attention at any time.


brocolli @brocolli08e6
0 Followers 57 Following
Era Ortiz @EraOrtiz240991
38 Followers 3K Following
🚩Uttam 🇮🇳�... @UVJOSHI
618 Followers 4K Following “राष्ट्राय स्वाहा,इदं राष्ट्राय इदं न मम” Chess my passion, RTs are not endorsements, option trading. https://t.co/UXk4oUfica
𝕾𝖜𝖊𝖙𝖆0... @Sweta0008
604 Followers 324 Following 𝔗𝔥𝔢 𝔖𝔱𝔯𝔲𝔤𝔤𝔩𝔢 𝔬𝔣 𝔅𝔢𝔦𝔫𝔤 𝔞 𝔓𝔯𝔬𝔣𝔢𝔰𝔰𝔦𝔬𝔫𝔞𝔩 𝔗𝔯𝔞𝔡𝔢𝔯,𝔏𝔬𝔳𝔢 𝔐𝔲𝔰𝔦𝔠 𝔞𝔫𝔡 𝔗𝔯𝔞𝔳𝔢𝔩
GratitudeSoup @GratitudeSoup
1.0M Followers 208K Following
Arijit De @itsarijeet
137 Followers 999 Following
Ashish Usha Agarwal �... @Ashish_HG
9K Followers 808 Following National Media Convenor, @BJP4India | Political Comms | Grassroots Politics | EMBA & MSW | First-Gen Politician | Inspired by PM Modi Ji | Maa’s Blessings 🇮🇳
Himanshu Yadav @HimashuYadav07
5K Followers 671 Following
Sameer Nadiger @NadigerSameer
18 Followers 48 Following
Dr. Mukul Agrawal @drmukulagrawal
20K Followers 247 Following Zerodha Broking Ltd.: SEBI Registration no.: INZ000031633 | 3x TEDx Speaker 2.5M+ Followers NSE AP reg. no.: AP2516003931
Donald J. Trump @DonaldTrump
2.1M Followers 7 Following Visit the official Donald J. Trump Twitter handle @realDonaldTrump. https://t.co/HyNW4tByaR

Ashish Kumar @BaapofOption
28K Followers 2K Following An Engineer who became a Trader 😅 || Stock Market Life Long Learner || Taurus 🐂 || Stray Animals Lover || धर्मो रक्षति रक्षितः || Sanatan Dharma 🙏💚
Ashwini Bhide @AshwiniBhide
118K Followers 479 Following IAS officer. Municipal Commissioner of Mumbai Municipal Corporation & MD Mumbai Metro corporation. 18 years in urban infra sector. RTs not endorsement.
BhikuMhatre @MumbaichaDon
235K Followers 3K Following Professor in Finance with Acute acumen in Politics & International Affairs. Speak Truth even if Bitter. Compelled to Swim Against Tide sometimes...to say FACTS.
Neeraj Chopra @Neeraj_chopra1
1.0M Followers 132 Following Indian Track & Field athlete. Javelin thrower 🇮🇳 For queries: [email protected]
Donald J. Trump @realDonaldTrump
111.8M Followers 53 Following 45th & 47th President of the United States of America🇺🇸
Mrs Anjali Damania @anjali_damania
144K Followers 1K Following Anti Corruption Activist who will only work in the best interest of our country. https://t.co/mRb5XAaGF5
Hindenburg Research @HindenburgRes
849K Followers 0 Following Popped bubbles as we saw them, including our own. We expressed strong opinions. Not investment advice.
BBC News Marathi @bbcnewsmarathi
345K Followers 58 Following नमस्कार, बीबीसी मराठी तुमच्यापर्यंत जगभरातील महत्त्वाच्या बातम्या आणि रंजक गोष्टी आणत असतं. रिट्वीट करायला विसरू नका. बीबीसीसाठी ‘कलेक्टिव्ह न्यूजरूम’चं प्रकाशन
Insider Paper @TheInsiderPaper
491K Followers 1 Following Insider Paper is your source for Breaking News and Developing Stories.
Market RebellionHQ @RebellioMarket
217K Followers 199 Following Empowering Traders in Stocks, AI & Blockchain. Dm for Paid Promotion:
Gaurav Maheshawari @GMaheshawari
7 Followers 56 Following
Real Estate Quikr @RealEstate_In
89 Followers 0 Following Buy, Sell or rent properties in India. Post free ads on Quikr Classifieds.
RedboxGlobal India @REDBOXINDIA
448K Followers 101 Following Indian Financial Audio news via @FirstSquawk Covering Indian breaking News Real time Instagram : https://t.co/A0Ml8J34vM
TEJASWWINI @tejaswwini
66K Followers 424 Following Actor- Films, Television & Theatre. Winner of Spain International Film Festival Awards! Nominee in Asia Pacific Screen Awards, Australia, Views are Personal !
Trinkerr @Trinkerr_IN
23K Followers 154 Following Trinkerr is transforming the trading experience in India with the help of ready-made algos crafted by industry experts.
FII DII Data @fiidiidata
84K Followers 8 Following FII DII Activity today in NSE, BSE. FIIs = Foreign Institutional Investors. DIIs = Domestic Institutional Investors. FII DII data in Indian stock exchanges.
PIB India @PIB_India
3.1M Followers 226 Following Press Information Bureau. Nodal agency for communicating to media on behalf of #Government of #India. In Hindi: @pibhindi For Fact Check: @PIBFactCheck
Nirmala Sitharaman Of... @nsitharamanoffc
737K Followers 1K Following Office of Smt. @nsitharaman; Minister of Finance and Corporate Affairs, MP (RS) representing Karnataka

Thirsty for pussy.�... @SajidSa88377168
767 Followers 1K Following
R. S. Salokhe @RSSalokhe1
7 Followers 34 Following
CESC Limited @CESCLimited
25K Followers 8 Following CESC Limited is the flagship company of RP-Sanjiv Goenka Group. It supplies electricity in Kolkata & Howrah since 1899.
Yeshupal Vasave @YeshupalV
26 Followers 72 Following
Stock Market का �... @krunalparab_
62K Followers 29 Following It's difficult to explain, but I'm here to show you the 2nd side of Stock Market using Supply & Demand Zones 🇮🇳 | Equity is 💎 | SEBI Unregistered!
desi mojito @desimojito
405K Followers 1K Following Journalist l News | Sarcasm l Politics l Humour l Cricket l Satrangi blood group🏳️🌈
Gaur Gopal Das @gaurgopald
191K Followers 31 Following A personal coach, monk, author, lifestyle & #motivational strategist, sharing deeper #spiritual insights with the world.

Kangana Ranaut @KanganaTeam
2.9M Followers 322 Following Member of Parliament-Mandi LS, BJP, Filmmaker/ writer. Padmashri, 4 national awards for 5 performances as an actor.
Pawan Arora @pawanaroraleo
71K Followers 226 Following Stopped Tracking after winning 20+ 60 Day Challenges Zerodha 60D Challenge Interview https://t.co/5tKSFlJsWJ
Ruth.Reynaeg29 @reynaeg29
453 Followers 1K Following Baton Rouge🦉24yo. Chaturb@te girl😌💜Visit my profile to chat and meet me:
Urfi javed @Urfijaved7
79K Followers 23 Following Public figure / model / Actress Page dedicated to Urfi Javed Fan page 😊 Follow fast ❤️
i-Trade - DJ @ITRADE191
106K Followers 55 Following IF U WANT TO WIN 🏆THE GAME ,U HAVE TO BE IN THE GAME ..I LIKE TO PLAY NIFTY 🙏
Ajay Bagga @Ajay_Bagga
298K Followers 6K Following Banker,CEO,Successful Long Term Investor,StartUp Mentor,Global Macros Commentator with over 10000 TV shows. https://t.co/X9R0nNd45Q
Dr. Rakesh Bansal @iamrakeshbansal
350K Followers 51 Following 25+ years in stock market 💹📈. Author of 3 Books .Contact @ Ph. 9560884223 WhatsApp: 9996161879. SEBI Registration number INH100008984
Vivek Bajaj @vivbajaj
569K Followers 926 Following 20+ Years learner of Stock Market My Whatsapp Channel link: https://t.co/5o1s3QVj4M
Team Neha @NehaFNO
36K Followers 22 Following Stock Market Related Tweets Are Just For Educational Purpose Only, Not Registered with SEBI, Account is handled by TEAM NEHA
Paytm Money @PaytmMoney
134K Followers 8 Following Explore Stocks, Mutual Funds & ETFs on Paytm Money. Investing made accessible for every Indian. 🇮🇳 SEBI registrations: https://t.co/jsz0iFHBy9
lakshmi @lakshmitrader5
254 Followers 156 Following I am an Indian by birth. investor, trader, tecnical analyst in equity. All calls are only education purpose. Mentor: Swati pawar
Aarati Krishnan @AaratiKrishnan
21K Followers 607 Following Track macros and markets, investing since late 90s. Macros and markets, data-based analysis and opinion. https://t.co/MKMlmxr3XmYou might like

















